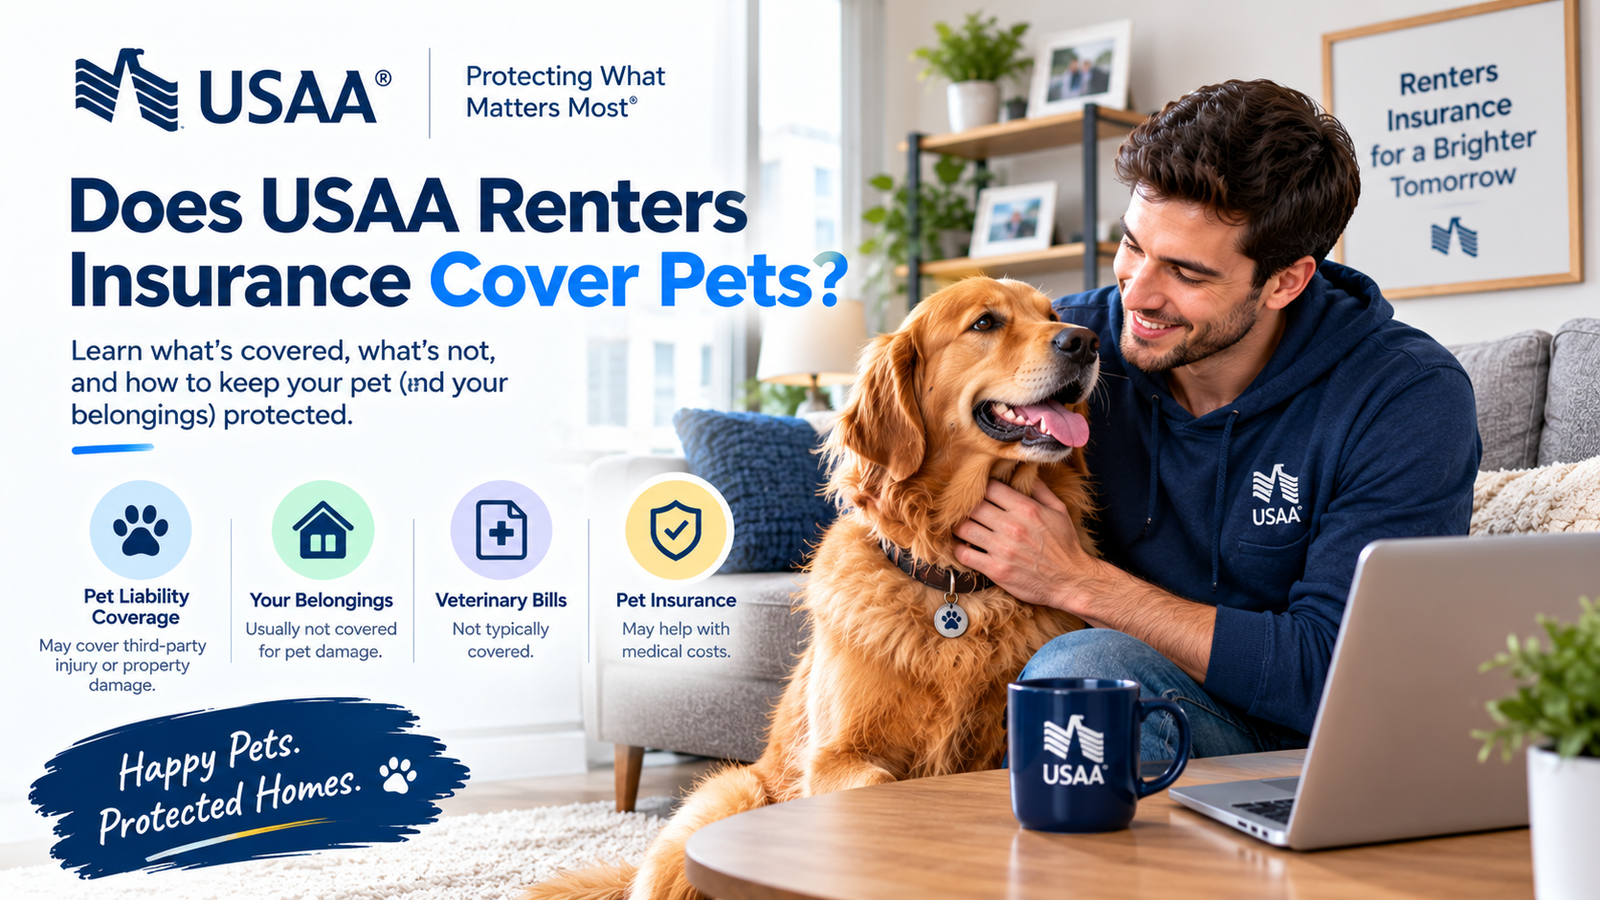
Does USAA renters insurance cover pets? USAA renters insurance may cover eligible third-party injury and property-damage claims involving your pet through personal liability coverage. However, coverage depends on your policy, state, exclusions and the circumstances of the incident.
Veterinary bills and damage your pet causes to your own belongings are generally not covered by renters insurance. Separate pet insurance may help with eligible veterinary expenses.
For a broader overview of insurance products, read our guide to private medical insurance, auto coverage, and affordable renters insurance .
Disclaimer: This article provides general information and is not insurance or legal advice. Coverage varies by state, policy and individual circumstances. Review your policy documents or speak with a licensed insurance professional before making a decision.
Does USAA renters insurance cover pets? Learn about pet liability coverage, dog bites, exclusions, policy limits, and separate pet insurance options.
Table of Contents
- How USAA Pet Liability Coverage Works
- What Pet Liability Coverage May Include
- What Renters Insurance Usually Does Not Cover
- USAA Renters Insurance vs. Pet Insurance
- Does USAA Renters Insurance Cover Dog Bites?
- Current U.S. Dog-Related Liability Statistics
- Does USAA Have Dog Breed Restrictions?
- Understanding Pet Liability Limits
- The Pet Coverage Gap Test
- What to Do After a Pet-Related Incident
- Frequently Asked Questions
- Final Answer
How USAA Pet Liability Coverage Works
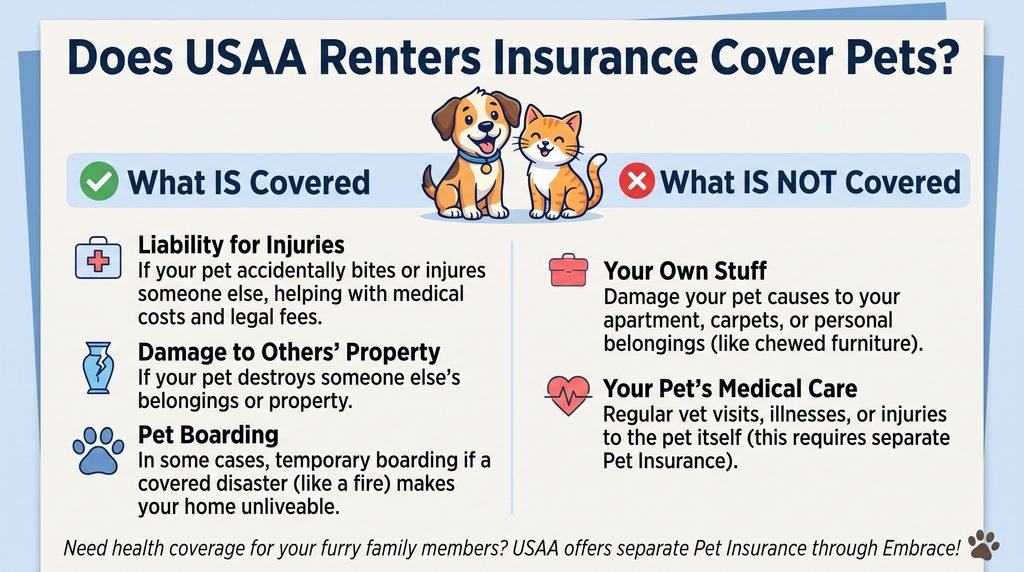
USAA’s U.S. renters insurance information explains that personal liability coverage may help when you are responsible for another person’s injury or damage to their property.
This protection may apply when your pet:
- Bites or injures a visitor
- Damages a neighbor’s property
- Causes someone to fall
- Damages another person’s belongings
- Creates a covered liability claim against you
For example, if your dog injures a visitor and you become legally responsible, your personal liability coverage may help with eligible costs up to the policy limit.
The policy may also help with certain legal defense costs, medical expenses or property-damage claims. However, the insurer must evaluate the incident under the applicable policy language.
Coverage can depend on:
- Your state
- The policy form
- Your liability limit
- Exclusions
- The animal involved
- The location of the incident
- Previous incidents
- The circumstances of the claim
Read the policy documents carefully and contact USAA if you need clarification. USAA Renters Insurance
What Pet Liability Coverage May Include
Pet liability coverage focuses on claims made by other people. Depending on the policy and circumstances, it may help with eligible:
- Medical expenses
- Property repairs
- Legal defense costs
- Covered settlements
- Court judgments
If your dog bites a visitor, the injured person may request payment for medical treatment. If your pet damages a neighbor’s belongings, the neighbor may request payment for repairs or replacement.
In both situations, the insurer may investigate:
- What happened
- Whether you were legally responsible
- Whether the incident was accidental
- Whether an exclusion applies
- Whether the claim falls within the policy limit
A general article cannot guarantee coverage for a specific incident. Only the applicable policy documents and claim review can determine whether the insurer will pay.
Liability Coverage Is Not Pet Health Insurance
Pet owners often use the phrase “pet coverage” to describe several different risks. These risks should be separated:
- Your pet injures another person.
- Your pet damages someone else property.
- Your pet needs veterinary treatment.
- Your pet damages the rental home.
Renters insurance may help with the first two risks when the policy applies. Pet insurance may help with eligible veterinary expenses. Your lease may determine your responsibility for damage to the rental property.
This distinction is important because having renters insurance does not mean that every pet-related expense is covered.
What Renters Insurance Usually Does Not Cover
Renters insurance generally does not cover:
- Veterinary bills for your pet
- Routine examinations
- Vaccinations
- Illness treatment
- Damage to your own furniture
- Scratched doors or floors
- Carpet stains caused by your pet
- Intentional damage
- Losses excluded by the policy
Veterinary Bills
Renters insurance is generally not designed to pay for your pet’s illness, surgery, medication or routine care.
Separate pet insurance may help with eligible veterinary expenses, depending on the plan, deductible, reimbursement rate and exclusions.
Damage to Your Own Belongings
If your pet chews your furniture, damages your clothing or scratches your personal property, renters insurance generally does not treat that as a covered liability claim.
Personal property coverage usually applies to covered causes of loss, not every type of accidental damage inside your rental.
Damage to the Rental Home
If your pet damages flooring, doors, walls, carpeting or other parts of the rental property, your lease may make you responsible for the repair costs.
Review your lease and renters policy together. Insurance coverage and lease responsibility are separate matters.
USAA Renters Insurance vs. Pet Insurance
Renters insurance and pet insurance protect different risks.
| Coverage | Main purpose | Veterinary bills |
|---|---|---|
| USAA renters insurance | Personal property and eligible liability claims | Generally no |
| Pet insurance through Embrace | Eligible veterinary expenses | May help, subject to the plan |
| Landlord insurance | Certain risks involving the building | No |
| Umbrella insurance | Additional personal liability protection | No |
USAA offers pet insurance through Embrace for eligible dogs and cats. The available information describes coverage options for eligible accidents and illnesses, while exclusions and reimbursement rules depend on the selected plan. USAA Pet Insurance
Pet insurance does not replace renters insurance. It may help with an eligible veterinary bill, but it generally does not defend you against a claim from someone who says your pet injured them.
What Pet Insurance May Help Cover
Depending on the selected plan, pet insurance may help with eligible expenses related to:
- Accidents
- Illnesses
- Surgery
- Hospitalization
- Diagnostic testing
- Emergency treatment
Pre existing conditions, routine care and other exclusions may apply. Review the plan documents carefully before purchasing.
Does USAA Renters Insurance Cover Dog Bites?
A covered dog-bite claim may qualify for personal liability protection, depending on your policy and the circumstances.
The insurer may consider:
- Whether you are legally responsible
- Where the incident occurred
- Whether the dog was disclosed
- Whether a previous incident exists
- Whether an exclusion applies
- Whether the claim exceeds the policy limit
- Whether the injury resulted from a covered situation
USAA’s renters insurance information explains that renters insurance may help protect you from covered liability claims involving bodily injury or property damage. USAA Renters Insurance Coverage
Do not assume that USAA will cover every dog bite. The insurer must assess the applicable policy terms, exclusions and facts.
Current U.S. Dog-Related Liability Statistics
Dog-related injuries can create significant financial costs. According to the Insurance Information Institute and State Farm, U.S. insurers recorded 28,450 dog-bite and related injury claims in 2025.
The reported 2025 figures included:
| Statistic | 2025 figure |
|---|---|
| Dog-bite and related injury claims | 28,450 |
| Total claim value | Approximately $1.862 billion |
| Average claim cost | $65,450 |
| Increase in the number of claims | 25.6% |
| Increase in total claim value | 18.6% |
| Change in average claim cost | 5.5% decrease |
These figures describe reported industry claims and do not predict the result of an individual renters insurance claim. The data includes dog bites and other dog-related injuries. Dog-Related Injury Claims on the Rise in 2025 | Insurance Information Institute
The statistics show why pet owners should review their personal liability limit instead of assuming that a basic policy provides unlimited protection.
Does USAA Have Dog Breed Restrictions?
Do not assume that every dog breed is automatically covered or automatically excluded under every USAA renters policy.
Eligibility may depend on:
- State regulations
- The policy form
- The dog’s breed
- Previous bite history
- Aggressive behavior
- Underwriting rules
- Policy exclusions
- The type of incident
USAA’s public renters insurance information does not establish one universal breed rule for every state and policy. Before purchasing or renewing coverage, ask USAA:
- Is my dog eligible for liability coverage?
- Does a previous bite affect coverage?
- Are breed-related restrictions applicable in my state?
- What liability limit applies to my pet?
- Does coverage apply outside my rental home?
- Do I need an endorsement or additional policy?
Disclose your pet and any previous incidents accurately. Do not rely on a general breed list or online article as confirmation of coverage.
Understanding Pet Liability Limits
Your renters policy includes a personal liability limit. This limit represents the maximum amount the insurer may pay for covered claims, subject to the policy terms.
A claim may involve:
- Emergency medical care
- Ongoing treatment
- Lost income
- Legal defense
- Property repairs
- Settlement costs
- Court judgments
If a covered claim exceeds your policy limit, you may remain personally responsible for amounts that insurance does not cover.
What Should You Review?
Check the following items in your policy documents:
- Personal liability limit: The maximum amount available for covered liability claims.
- Medical payments to others: Whether this coverage applies and what limit is available.
- Exclusions: Circumstances, injuries or property damage that the policy does not cover.
- Policy conditions: Requirements that may affect claim payment.
- Defense provisions: How the policy handles legal defense for covered claims.
Should You Consider Umbrella Insurance?
An umbrella policy may provide additional liability protection above certain underlying insurance limits if the claim qualifies.
Umbrella policies have their own eligibility requirements, exclusions and underlying insurance conditions. Do not assume that an umbrella policy automatically covers every pet-related claim.
If you are concerned about a potentially expensive liability claim, ask your insurer whether additional protection is available. USAA Umbrella Insurance
The Pet Coverage Gap Test
Ask yourself these questions:
- If my pet injured someone tomorrow, would my liability limit be enough?
- If my pet needed expensive treatment, could I afford the veterinary bill?
- If my pet damaged the rental home, who would pay for repairs?
- Does my lease require special pet coverage?
- Have I disclosed my pet accurately to the insurer?
- Do I understand the policy’s animal-related exclusions?
Your answers may show that you need a combination of renters insurance, pet insurance, higher liability limits or additional protection.
This risk-based approach is more useful than asking only whether a pet is “covered.” It helps you understand which policy addresses each potential expense.
How to Check Whether Your Pet Is Covered
Use these steps before relying on your policy:
- Review the declarations page.
- Read the personal liability section.
- Check the exclusions.
- Look for animal-related conditions.
- Confirm your liability limit.
- Ask whether your pet is eligible.
- Disclose previous incidents.
- Request clarification from USAA if any term is unclear.
Keep written confirmation and policy documents in a safe place.
What to Do After a Pet-Related Incident
If your pet injures someone or damages property:
- Protect everyone’s safety.
- Secure your pet.
- Arrange medical care if necessary.
- Exchange contact information.
- Photograph the damage when it is safe.
- Avoid promising payment or admitting legal fault.
- Report the incident to USAA promptly.
- Send legal letters or court documents to the insurer.
- Keep medical bills, photographs, receipts and messages.
Prompt reporting allows the insurer to investigate the incident and explain the next steps.
Do not ignore a demand letter or court document. Send legal papers to your insurer promptly and consider independent legal advice when appropriate.
You can also review the USAA renters insurance claims information .
Frequently Asked Questions
Does USAA renters insurance cover dog bites?
It may cover eligible dog-bite liability claims through personal liability coverage, subject to policy limits, exclusions and state-specific rules.
Does USAA renters insurance pay veterinary bills?
Usually, renters insurance does not pay veterinary bills. USAA offers separate pet insurance through Embrace for eligible dogs and cats. USAA Pet Insurance
Does renters insurance cover damage my pet causes to my apartment?
Pet damage to the rental unit may be excluded. Check your lease and policy to determine whether you are responsible for repairs.
Should I buy pet insurance and renters insurance?
They protect different risks. Renters insurance may help with eligible liability claims, while pet insurance may help with covered veterinary expenses.
Does renters insurance cover pets outside the home?
Coverage depends on the policy wording and type of incident. Ask USAA whether your liability coverage applies when your pet causes an injury or property-damage claim away from your rental home.
Does USAA automatically cover every dog breed?
Do not assume that every breed receives the same treatment. Ask USAA about the rules that apply to your specific policy, state and pet.
Should I increase my renters liability limit?
A higher limit may provide stronger protection, but it may also increase your premium. Consider your assets, pet’s history and household risks before changing coverage.
Final Answer
USAA renters insurance may cover certain pet-related liability claims, but it does not cover every pet-related expense or incident.
If your pet injures someone or damages another person’s property, personal liability coverage may help when the claim qualifies under your policy. Veterinary bills, damage to your own belongings and excluded incidents generally require a different approach to protection.
The practical approach is to:
- Use renters insurance for personal property and eligible liability protection.
- Consider pet insurance for eligible veterinary expenses.
- Review your lease for rental-property responsibilities.
- Ask about higher liability limits or umbrella insurance if your potential liability exceeds your current protection.
- Confirm your pet’s eligibility directly with USAA.
Understanding the difference between renters insurance and pet insurance can help you identify gaps in coverage and make better-informed decisions about protecting yourself, your belongings and your pet.
About the Author
Written by: Rana Mustaqeem Sarwar
Email: ranamustaqeemsarwar@bodybmicalculatormale.com
Phone: +1 (571) 571-4816
Last updated: October 25, 2026
Rana Mustaqeem Sarwar creates informational content about insurance, health and personal finance topics. This article is for general information and is not insurance or legal advice.
Contact response time: We reply within 24 to 48 hours on business days.